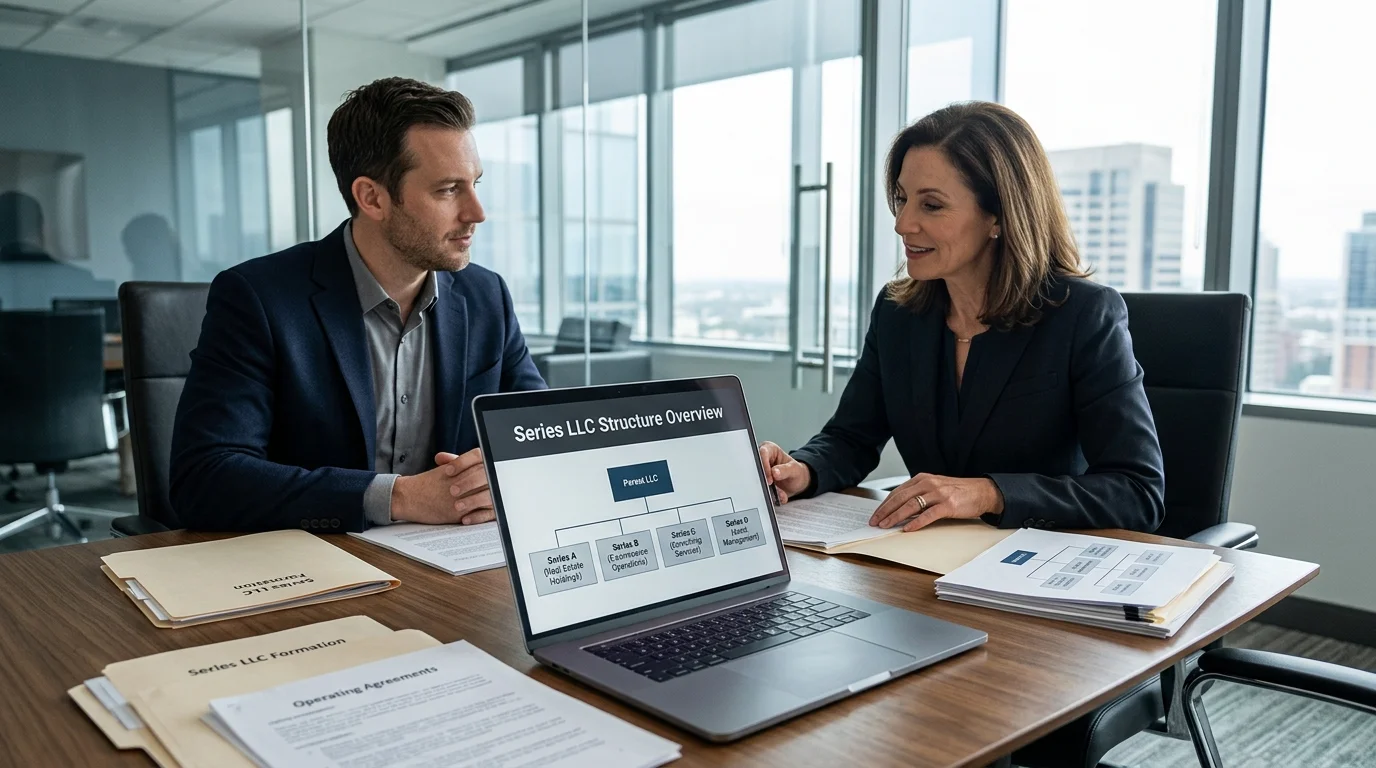
A series LLC is one parent company that can spin off internal cells, each holding its own assets and, on paper, its own debts. Property investors like the idea because ten rental houses can sit in ten cells under a single state filing. The catch is that the walls between those cells have never been fully tested in court.
Short answer: you form one company with your state, then create numbered cells inside it. Each cell keeps separate books, separate assets, and separate contracts. If a tenant sues cell three, only cell three’s assets should be at risk. Roughly twenty states plus the District of Columbia authorize some version of this.
Key takeaways before you file anything
- One state filing can cover many cells, which is why the structure looks cheap next to ten separate companies.
- The savings shrink fast once you add bookkeeping, insurance, and a separate bank account per cell.
- Federal tax treatment rests on a proposed rule from 2010 that was never finalised.
- No controlling court decision confirms the shield holds outside the forming state or inside bankruptcy.
- California charges each cell doing business there its own annual tax, which erases the savings.
Fees I confirmed on the state’s own website
Most guides recycle a fee table someone wrote years ago. These four numbers came from government sites in August 2026, and I have left out every figure I could not confirm the same way.
| State | What the state calls it | Confirmed fee | Worth knowing |
|---|---|---|---|
| Delaware | Registered series | $90 to file each certificate of registered series | Plus $100 per registered series in annual franchise tax |
| Texas | Protected series and registered series | $300 for the parent certificate of formation | A protected series needs no separate filing at all |
| Florida | Protected series | $25 per designation of protected series | Online filing only, and the law took effect July 1, 2026 |
| California | No home-state statute | $800 annual tax per cell doing business there | Each cell files its own Form 568 |
How the structure works in practice
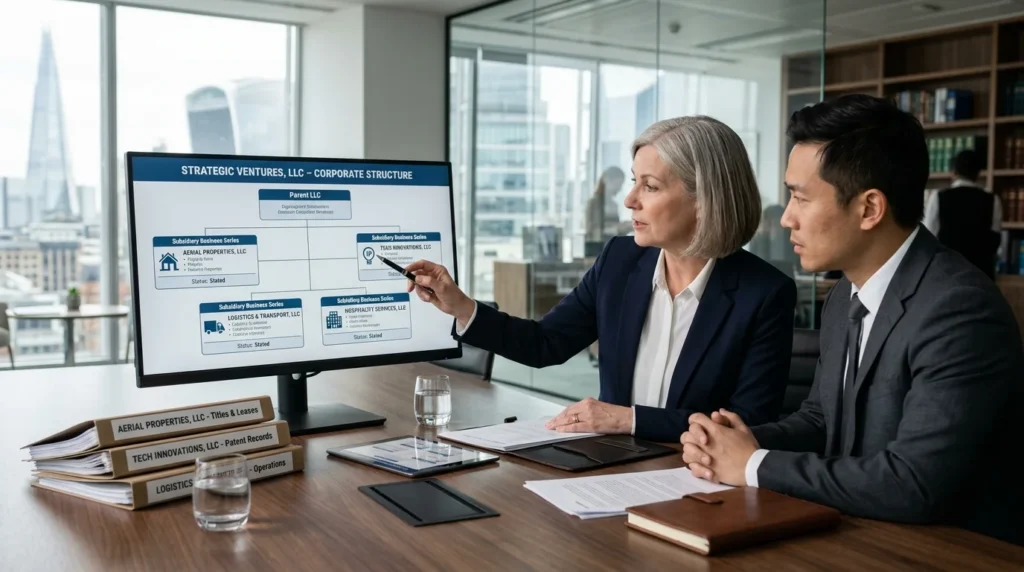
Think of a filing cabinet. The cabinet is the company your state registers. Each drawer is a cell with its own name, its own assets, and its own owners if you want it that way. Nothing stops you from putting a food truck in one drawer, and a duplex in the next, and nothing stops you from adding drawers later.
The drawers only stay sealed if you do the unglamorous work. Texas spells out three conditions in its business code. Records have to account for each cell’s assets separately. Your company agreement has to state that the liability limits apply. Finally, the public certificate of formation has to carry notice of those limits. Miss any one and the drawers become one big pile.
That recordkeeping burden is where owners get caught out. A restaurant group with four locations in four cells still needs four ledgers, four insurance certificates and four sets of payroll records. Anyone already dealing with last-minute staffing problems for restaurants knows how quickly shared staff and shared petty cash blur those lines. Blurred lines are exactly what a plaintiff’s attorney looks for.
Where you can form a series LLC right now
Delaware wrote the first statute in 1996. Texas, Illinois, Nevada, Utah, Oklahoma, Tennessee, Iowa and Kansas followed. So did Missouri, Montana, Alabama, Arkansas, Indiana, Nebraska, North Dakota and South Dakota. Virginia, Wisconsin, Wyoming and the District of Columbia round out the list. Florida joined the list on July 1, 2026.
The newer statutes mostly track the Uniform Protected Series Act, finalised by the Uniform Law Commission in 2017. That model act coined the term “protected series” and defined it. A protected series is an internal division whose assets sit beyond the reach of the parent company’s creditors, as long as the statutory conditions hold. It also forces a public paper trail, so outsiders can tell which cells exist.
Delaware and Texas now offer two flavors. A protected series lives entirely in your internal agreement and never touches the state’s records. A registered series gets its own filing, its own name in the public index, and its own certificate of good standing. Lenders and title companies increasingly ask for the registered version, because they cannot run a lien search against something the state has never heard of.
What the IRS actually says about taxes
Here is the fact most explainers skip. Treasury and the IRS published a proposed rule, REG-119921-09, on September 14, 2010. It would treat each series as an entity formed under local law for federal tax purposes. Sixteen years later, it is still a proposed rule, never finalized.
In practice, most tax preparers follow the proposed approach and classify each cell of a series LLC separately. A single-member cell is disregarded, a multi-member cell files a partnership return, and a cell can elect corporate treatment. Your state may take a different view entirely. California’s 2025 Form 568 booklet says each cell registered or doing business in the state files its own return and pays its own annual tax.
State franchise tax is where the arithmetic turns against you.
According to the Delaware Code, Title 6, section 18-1107(b), each registered series owes an annual tax of $100. Twelve cells means $1,200 a year in Delaware franchise tax alone. Add your accountant, your registered agent, and a dozen returns on top of that.
EINs, bank accounts, and the paperwork nobody warns you about
Any cell that files its own federal return, hires staff, or opens a bank account needs its own EIN. Applications are free and take minutes online. Skipping them is a false economy, because a shared tax ID is strong evidence that you treated the cells as one business.
Banks are the real friction.
Many branch staff have never seen this structure, and a few institutions refuse outright. Bring the parent certificate of formation, the company agreement, the certificate of registered series if you have one, and the EIN letter for that specific cell. Expect to explain the whole arrangement twice, and expect a manager to call the legal department before anything opens.
Each cell also tends to grow its own public face over time. Separate trade names mean separate listings, separate reviews, and separate websites, which is a marketing cost people forget to budget. If you plan to run distinct brands, read up on what an on-page SEO service includes before you register four domains you cannot maintain.
The genuinely unsettled part
Now the honest caveat. Every statute promises the shield, and no appellate court has definitively confirmed that a court outside the forming state must honor it. A judge in a state with no series statute applies its own law on internal affairs, and reasonable lawyers disagree about the outcome.
Bankruptcy is murkier still. The Bankruptcy Code was written without cells in mind. No settled answer exists on whether one cell can file alone, or whether a trustee can pull sister cells in.
Anyone telling you that question is closed is selling something.
Insurance carriers add their own wrinkle. Some will not write a policy naming a cell as the insured. That pushes you back to a parent-level policy and quietly undercuts the separation you paid for, so ask your carrier before you file rather than after.
Who this fits, and who should walk away

Good fit: an investor holding several properties in one of the authorizing states, with a bookkeeper, an attorney, and no plans to expand into states that have no statute. Also decent for fund managers running parallel deals under one umbrella.
Poor fit: anyone operating across state lines, anyone who wants outside investors in one venture only, and anyone who will not keep separate books.
Multi-venture owners, the sort profiled in our piece on Jim McIngvale’s furniture empire, usually end up with plain standalone companies. Banks, lenders and buyers understand a standalone company instantly, which matters on the day you sell one piece and keep the rest.
There is also a quieter argument for simplicity. Ten ordinary companies in Wyoming cost a few hundred dollars each per year, carry no legal ambiguity, and survive a move to another state without drama. Compare that total against the fees above before you commit. If you want to go deeper, read Assault vs. Battery.
Your next step
Write down how many separate assets you actually hold, which states they sit in, and what your bookkeeper charges per entity. Take that one page to a business attorney licensed where you operate and ask a direct question: does this structure beat plain separate companies for my facts? If the answer takes more than ten minutes to explain, that is your answer.
Frequently asked questions
It needs one if it files a separate return, employs anyone, or opens a bank account. Most owners get one per cell anyway, because it strengthens the separation argument and costs nothing.
Yes, in practice. Commingled cash is the single fastest way to lose the shield, and it is the first thing an opposing lawyer requests in discovery.
Usually yes, by amending the certificate of formation to add the required notice and updating the company agreement. Your state may charge an amendment fee, and transferring assets into cells can trigger transfer taxes.
Only at the state filing window. Once you count per-cell franchise tax, bookkeeping, insurance, and tax returns, the gap narrows sharply and sometimes reverses.
States with their own statutes generally register the parent as a foreign company and treat the cells according to home-state law. States without a statute give you no guarantee at all.